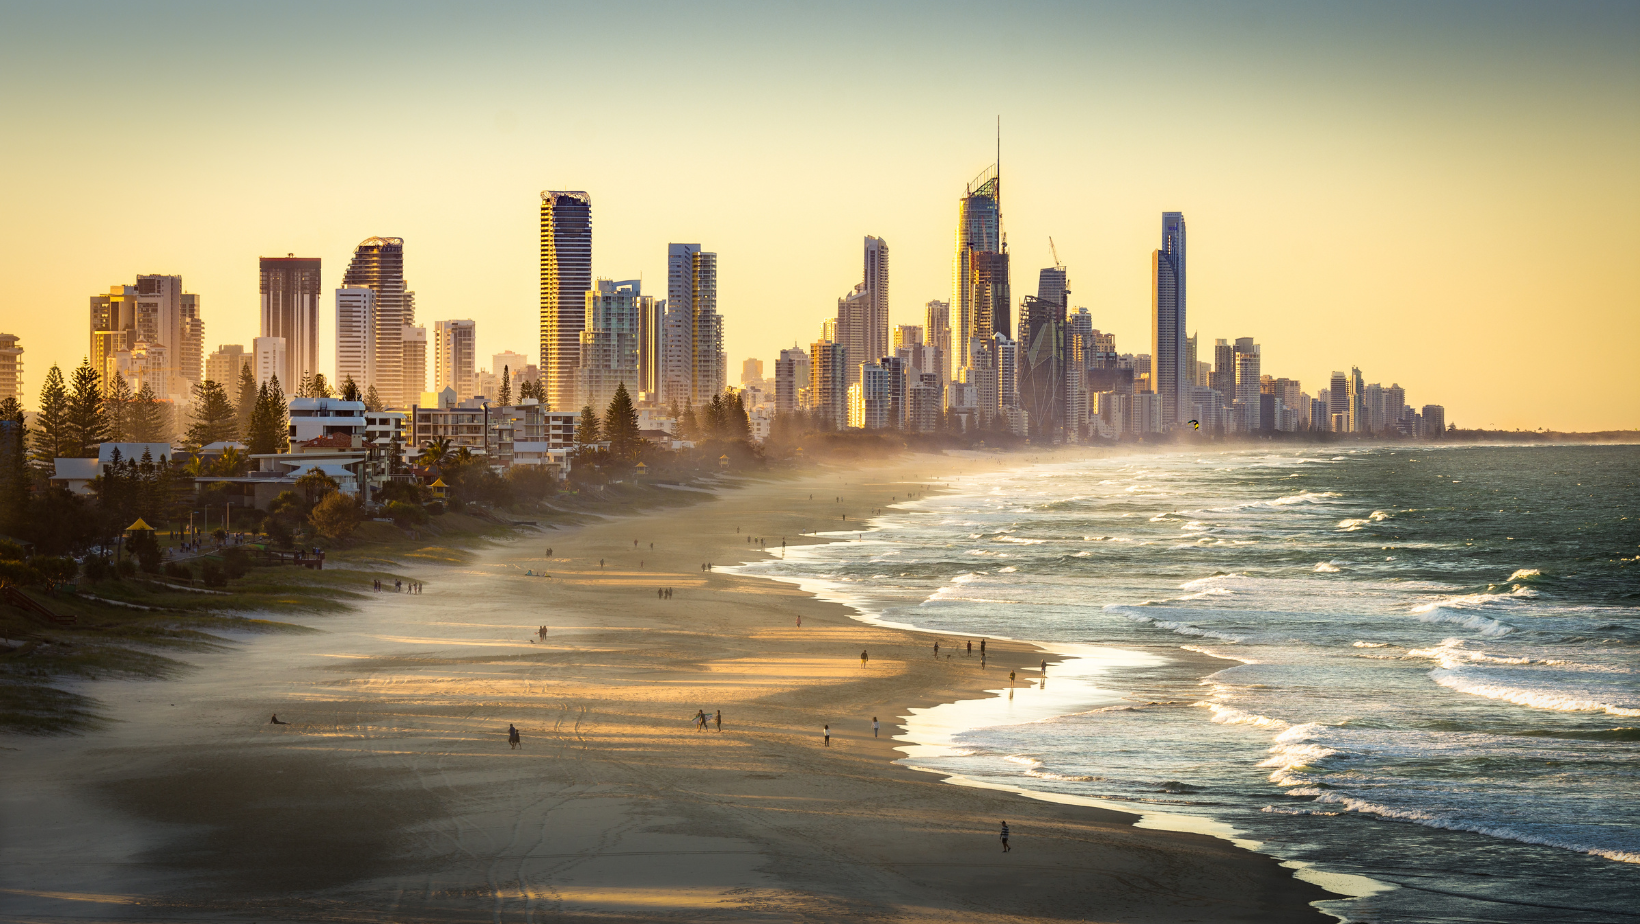
In early September we wrote that the Gold Coast was defying the national slump, edging up in July while Brisbane and the rest of the country slipped. That was a snapshot of one month. Six weeks later, the picture looks quite different.
Here’s what the latest data shows, why it’s happening, and what it means if you’re buying, selling or sitting on a Gold Coast loan. This update is based on data available in mid October 2026.
What the data says
The first thing to know is that the Gold Coast doesn’t get its own line in Cotality’s monthly index. It sits inside the regional Queensland figures, so the Gold Coast picture has to be pieced together from several sources.
The national backdrop is weak. Cotality’s Home Value Index fell 1.1% in September, the sixth straight monthly fall, taking values 5.2% below the March peak. Brisbane had the sharpest drop of any capital at 1.5%, and 97% of capital city suburbs fell over the past three months (Cotality, ABC News).
Regional Queensland, which includes the Gold Coast, eased too. It fell 0.9% in September, though it was still 6.3% higher over the year (GC Prestige, citing Cotality). Sold prices lag, so they tend to show falls later than asking prices do.
Asking prices are where the weakness shows first. SQM Research reports that Gold Coast median house asking prices have fallen 8.6% since March, and unit asking prices have dropped 16.4% since February. SQM’s Louis Christopher described the falls as uniform across the city (MacroBusiness, citing SQM Research).
It’s worth being clear about what asking prices are. They show what sellers are hoping for, not what buyers ultimately pay. But when asking prices fall this far, sold prices usually follow.
For context, Cotality data to June put the Gold Coast median house price at around $1.35 million and the median unit price at about $900,000. Those figures predate the recent falls.
Why it’s happening
Interest rates. The RBA has lifted the cash rate four times this year to 4.60%, and the big four banks passed on the latest 0.25% rise in full from 9 October (MPA). Westpac and ANZ estimate that adds about $79 a month on a $500,000 loan.
Borrowing capacity. Lenders assess repayments at 3 percentage points above the loan rate (APRA). Every rate rise lowers how much buyers can borrow, which takes pressure off prices.
A market that ran hot. SQM’s view is that the Gold Coast had become overvalued, with a large increase in apartment approvals since the pandemic. The Gold Coast has also long been a market that swings hard in both directions.
More falls may be ahead. Cotality’s research director, Tim Lawless, expects values to keep falling into 2027, and said a 10% to 15% drop nationally is a fairly reasonable estimate (ABC News). That’s one expert’s forecast, not a certainty.
What it means for you
If you’re buying
- You have more room to negotiate. Falling prices and slower sales usually mean more room to move on price and terms.
- Your borrowing capacity may have shrunk. A pre-approval from earlier in the year was assessed at a lower rate. It’s worth having it refreshed.
- Valuations matter more. In a falling market, a lender’s valuation can come in below the contract price, leaving a gap you’d need to cover with cash.
If you’re a first home buyer
Queensland’s first home concession gives a full exemption on established homes up to $700,000, tapering to nothing at $800,000 (Queensland Revenue Office). With the Gold Coast median unit price at about $900,000, many established homes fall outside that range. New homes have no price cap on the concession, which is worth knowing if you’re comparing options. Our guide to stamp duty by state has the full picture.
If you’re selling
Realistic pricing matters more than it did six months ago. If you’re buying your next home first, a bridging loan can help you avoid a rushed sale. Our Buy Your Dream Home page covers the options.
If you own and have a loan
- Your equity may have shrunk. Usable equity is 80% of your property’s value minus your loan, so a lower value reduces it by 80 cents for every dollar lost. See our home equity release page for how this works.
- It’s a good time to check your rate. The gap between your rate and what lenders offer new customers is worth a look. Start on our refinancing page.
If you’re an investor
Higher rates squeeze cash flow, and lenders apply a more conservative assessment to investment lending. Our investment loans page covers how lenders currently assess it.
What to do now
- Get a current estimate of your property’s value. Don’t rely on last year’s figure.
- Stress test your repayments. Check you’re comfortable if rates rise again, and remember the next RBA decision is on 3 November.
- Refresh your pre-approval if you’re buying.
- Look at your loan structure and rate if you’re refinancing.
- Speak to a broker before you commit. Lender policies on valuations, apartments and income differ.
Gold Coast suburb guides
We’ve written finance guides for several Gold Coast suburbs, including Coomera, Southport, Varsity Lakes and Arundel.
Talk to our Gold Coast team
The hfinance Gold Coast office is at Highland Park, and our team compares across 50+ lenders. If you’re buying, selling or refinancing on the Gold Coast and want to know where you stand, get in touch. You can also try our home loan calculator to see what different rates mean for your repayments.
This article is general information only and does not take into account your personal financial situation or objectives. Gold Coast property data comes from several sources that measure different things, including asking prices and sold prices, and figures can change quickly. Forecasts are opinions, not guarantees. Speak with an hfinance broker before making any lending decisions.